If you manage payroll or hiring: A W-2 reports wages paid to employees, and employers withhold taxes from those wages. A 1099 reports payments to independent contractors, who pay their own taxes. For payments made in 2026 and later, 1099-NEC and 1099-MISC forms are generally required once you pay a worker $2,000 or more, up from $600.
Understanding the Differences Between Forms W-2 and 1099
If you manage payroll or hiring, your role in understanding the difference between a W-2 and a 1099 is crucial. These forms help identify two distinct worker types—employees and independent contractors. You could face fines, tax issues, and serious payroll headaches without the correct classification. Your understanding and proper classification are key to staying compliant.
Understanding how these forms impact your processes will help you avoid costly errors and improve efficiency. Let’s explore who gets which form, the key differences, and how to make the right call at year-end. By doing so, you can ensure accuracy and avoid unnecessary costs.
What is a W-2?
Form W-2 is the go-to tax form for employees. It shows total wages earned, taxes withheld, and deductions for things like health insurance or retirement contributions—all the key information employees need to file their tax returns. As an employer, you must file W-2s with the Social Security Administration (SSA) and provide copies to your employees by January 31st. For 2026 wages, the deadline is February 1, 2027, because January 31 falls on a Sunday. If employees misplace their W-2, encourage them to visit the IRS website for a copy.
W-2s reflect a structured working relationship. You’re responsible for withholding income taxes and covering your share of Social Security, Medicare, and unemployment taxes. From the first paycheck to year-end reporting, everything flows into the W-2 to ensure accuracy and compliance.
Reporting W-2 Income for Employees
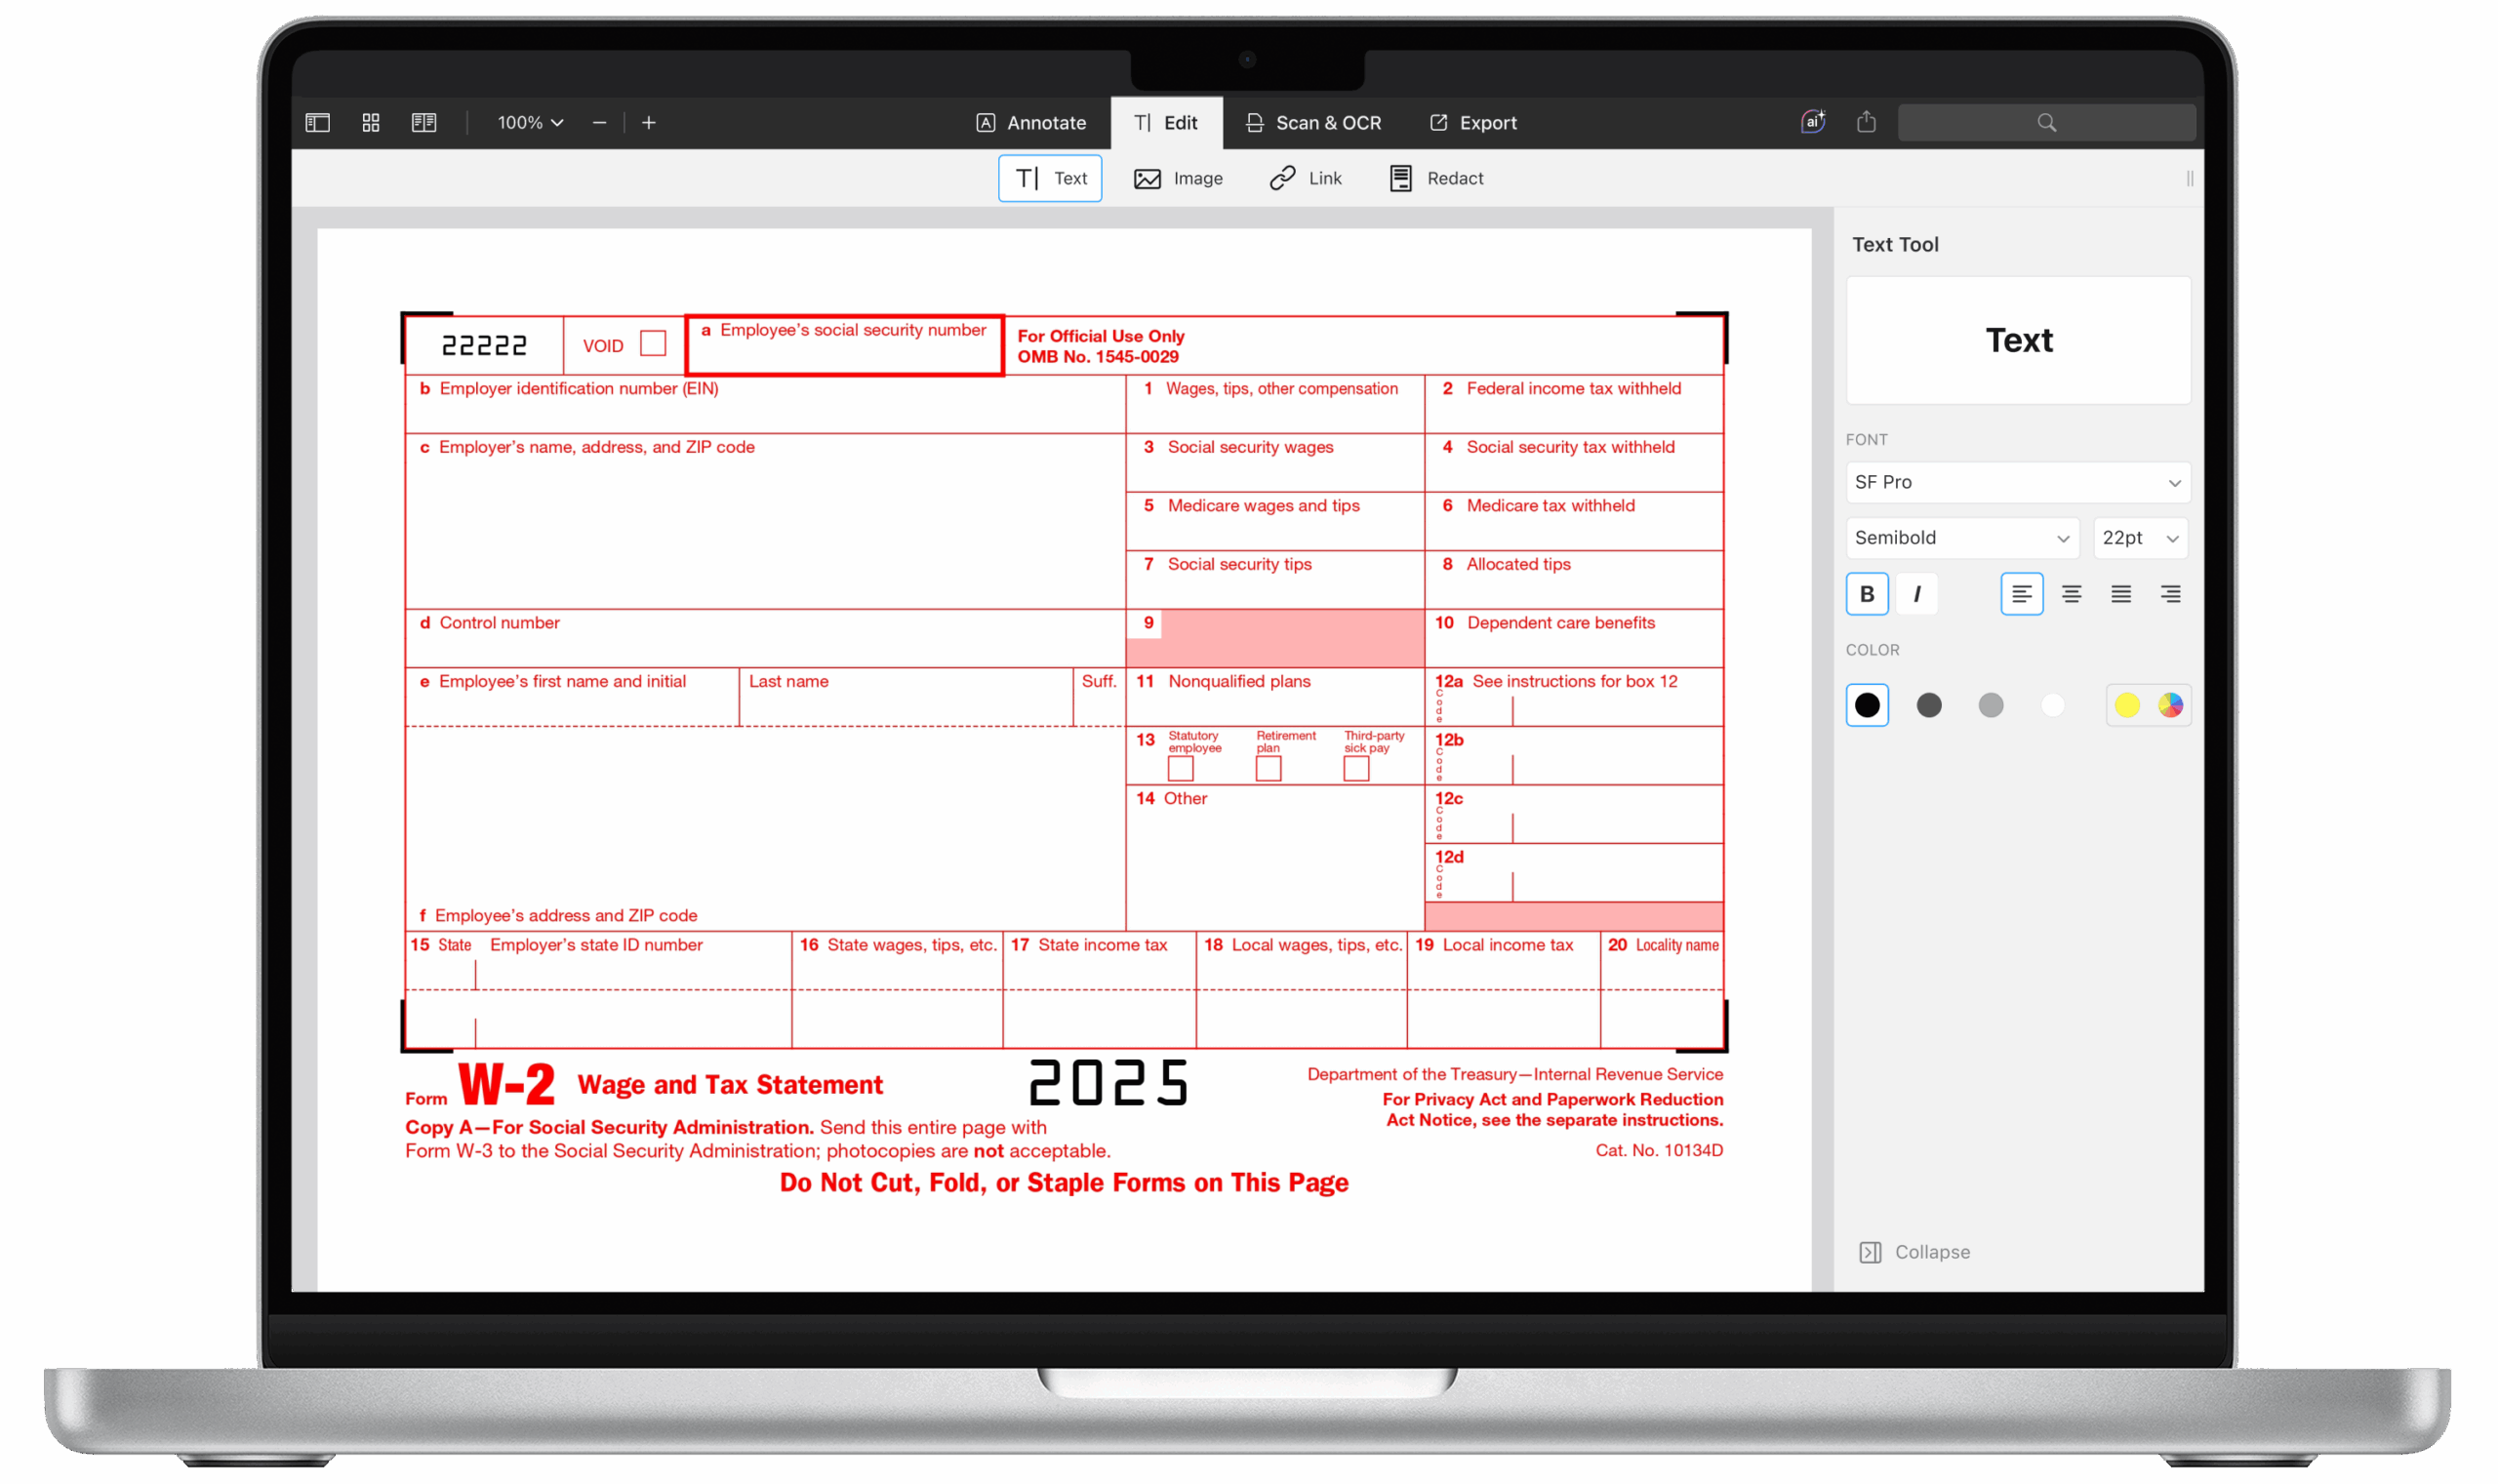
You must report each employee’s wages, tax withholdings, and employer-paid contributions as part of your year-end responsibilities. This requirement includes federal income tax, Social Security, Medicare, and unemployment (FUTA) taxes. Year-end reporting involves compiling and submitting this information to the appropriate tax authorities.
Social Security tax is split evenly between you and the employee at 6.2% each. The same goes for Medicare, with both sides contributing 1.45%. These amounts and any additional deductions are reflected on the employee’s W-2 and used to file their annual tax return.
What is a 1099?
Form 1099 is used for non-employees—typically independent contractors, freelancers, or consultants—who are paid $2,000 or more in a calendar year (for most payments made in 2026 and later, up from $600). The most common versions are 1099-NEC and 1099-MISC. Unlike W-2 workers, these individuals handle their taxes, so no withholdings are required from your side.
Issuing a 1099 signals a more flexible working relationship. Contractors usually set their schedules, use tools, and work with multiple clients. You must send them their 1099-NEC and file it with the IRS by January 31. For 2026 payments, that deadline is February 1, 2027. Getting this right helps you avoid costly missteps at tax time.
Reporting 1099 Income for Contractors
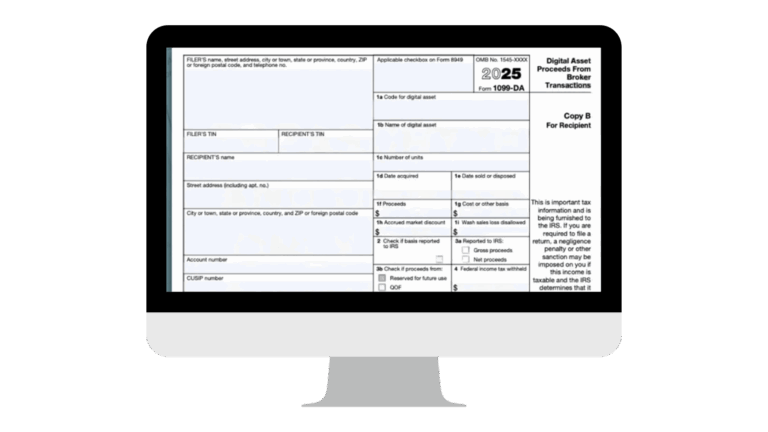
For independent contractors, you generally don’t withhold taxes but are responsible for reporting payments of $2,000 or more using Form 1099-NEC. Submit the form to the IRS and provide a copy to each contractor by January 31. The exception is backup withholding: if a contractor doesn’t give you a taxpayer identification number, you may need to withhold 24% of their payments and send it to the IRS.
What is Form 1099-NEC, and Who Receives It?
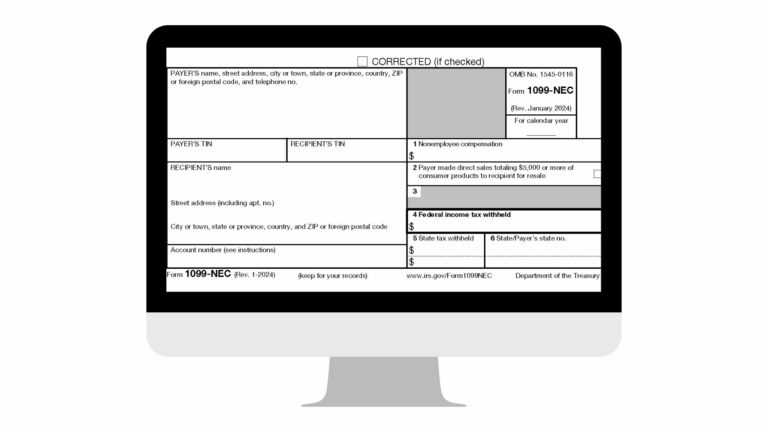
Form 1099-NEC reports non-employee compensation of $2,000 or more, typically paid to independent contractors or freelancers. If a worker isn’t classified as an employee and is paid $2,000 or more in a calendar year, you must issue a 1099-NEC and file it with the IRS, and in some cases, with state or local agencies.
These payments must also be reported using Form 1096 when submitting paper filings. The IRS requires electronic filing if you file 10 or more information returns of all types combined, so most employers with more than a few workers must e-file. To simplify year-end processing, verify contractor names, addresses, and Social Security numbers beforehand. Distributing 1099s can be quick and efficient if you use a payroll provider.
What is Form 1099-MISC?
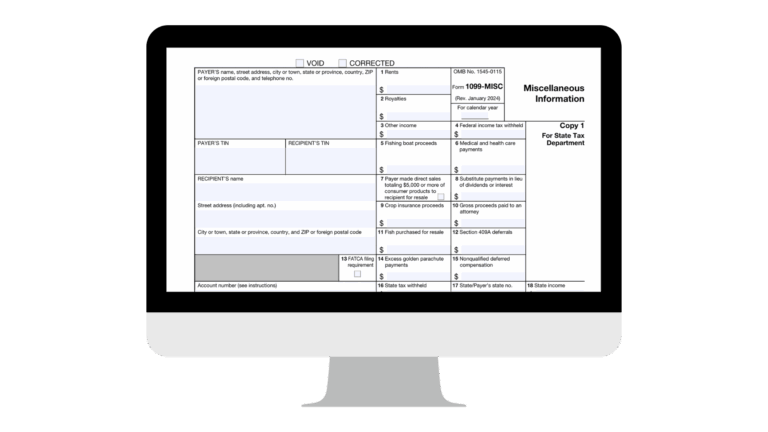
Form 1099-MISC reports miscellaneous income outside standard contractor compensation, generally $2,000 or more for most payments. Royalties of $10 or more are the main exception. Types of income to report include rent, prizes and awards, medical and health care payments, and gross proceeds paid to attorneys ($600 or more). Attorney fees for services go on Form 1099-NEC. Send 1099-MISC recipient copies by January 31 (February 1, 2027, for 2026 payments). File with the IRS by February 28 on paper or March 31 electronically. For 2026 payments, the paper deadline is March 1, 2027, because February 28 falls on a Sunday. Paper filers also submit Form 1096.
W-2 and 1099 Deadlines
| Deadline to Send Forms to Employees & Contractors | Deadline to File W-2 With Social Security Administration | Deadline to File 1099-NEC / 1099-MISC with the IRS |
| January 31st* | January 31st*: Employers should file forms along with a W-3 transmittal | 1099-NEC: January 31*. 1099-MISC: February 28* (paper) or March 31 (electronic). Paper filers include Form 1096. |
*If a due date falls on a weekend or holiday, it moves to the next business day. For 2026 forms filed in 2027, January 31 falls on a Sunday, so the deadline becomes Monday, February 1. The February 28 paper deadline for 1099-MISC also falls on a Sunday and becomes Monday, March 1. The March 31 electronic deadline is unchanged.
Difference in W-2 and 1099 Employees
Employment Status
-
W-2:
Issued to employees by their employers, who withhold taxes from employees’ salaries and forward those withholdings to the appropriate tax authorities.
-
1099:
Issued to independent contractors or freelancers responsible for paying their taxes.
Tax Withholding
-
W-2:
Employers withhold federal, state, and local taxes from employees’ paychecks.
-
1099:
Independent contractors must withhold taxes themselves and pay estimated taxes quarterly.
Benefits and Protections
-
W-2:
Workers frequently qualify for health insurance, pension plans, and unemployment benefits.
-
1099:
Independent contractors typically do not receive benefits from the payer.
Types of 1099 Workers
You can provide 1099s to several types of workers, and knowing these distinctions will streamline your recruiting process. Here’s a list of the most common types:
Freelancers
These individuals often work with organizations on a per-project basis. Some freelancers work with multiple businesses simultaneously, maximizing their earning potential. In addition, they usually choose when they can and can’t work and set their rates.
Consultants
Like freelancers, these individuals are self-employed. However, the difference lies in their skill set. Often, these individuals have unique or highly crafted experiences, education, and training that make their knowledge invaluable. These workers usually demand high compensation for their time and efforts.
Independent Contractors
Independent contractors are self-employed workers who offer their services to the public and run their own business. They usually use their own tools, set their own schedules, and work for more than one client. You pay them for the result, not for how they do the work, and they handle their own taxes.
Gig Workers
These individuals are similar to freelancers; however, their offerings and payouts differ. Because these workers usually opt to perform small jobs, they are often paid per task completed.
How to Determine if a Worker is an Employee or Independent Contractor
Worker classification impacts how you pay employer taxes and how your employees pay theirs. Here are the three categories the IRS looks at when making employment classifications:
1. Behavioral Control
Behavioral control demonstrates whether you have the right to direct or control how workers complete their tasks. If a business has the right to direct or control task completion, the worker gets classified as an employee. The employer does not have to handle how the work gets done as long as they own it. Behavioral control falls into the following categories:
Type of Instructions Given
Workers will likely be employees if they receive detailed instructions on when, where, and how to do their job. Instructions can include what tools to use, who to work with, and the order of tasks.
On the other hand, independent contractors typically receive less direction and have more control over how the work gets done. Even without direct instructions, an employer may still have behavioral control if they retain the right to dictate how results are achieved.
Degree of Instruction
Workers may be independent contractors if they’re told what to do but not how. While the level of instruction can vary by role, behavioral control may still exist if the employer retains the right to direct how results are achieved.
Evaluation System
If an evaluation system is in place that measures performance, then these factors would indicate an employee. However, if the evaluation system only measures the result, this could mean either an employee or an independent contractor.
Training
If an organization dictates how someone should perform the work or provides ongoing training, the worker is likely an employee. Independent contractors typically use their own methods.
2. Financial Control
Financial control refers to the facts determining whether or not an employer has the right to control economic aspects of the worker’s job. These categories include:
Significant Investment
Independent contractors often invest in their tools, but some employees do too. There’s no set dollar amount for what qualifies as a “significant investment,” and some roles require minimal expenses.
Unreimbursed Expenses
Unreimbursed expenses are more common for contractors, but some employees may have them too. Consider whether the worker regularly incurs fixed costs, even when not actively working.
Control Over Earnings and Client Base
Workers who invest in their tools, incur unreimbursed expenses, and risk financial loss are more likely to be independent contractors. They often promote their services, work with multiple clients, and operate openly in the marketplace.
Method of Payment
Employees are typically paid a consistent wage on a set schedule, while contractors are often paid a flat fee per project; however, hourly pay is also standard in some contract roles.
3. Type of Relationship
Type of relationship refers to facts about how the worker and employer perceive their relationship. These factors include the following categories:
Written Contracts
A written contract alone doesn’t define worker status; the working relationship matters.
Benefits and Duration of the Relationship
Offering benefits like health insurance, paid time off, or retirement plans typically indicates an employee relationship. Similarly, if the working relationship is expected to continue long-term, it’s more likely that the worker is an employee.
Independent contractors usually work on specific projects for a set period and do not receive traditional employee benefits, though the absence of benefits alone doesn’t guarantee contractor status.
Services Provided as Key Activity of the Business
If a worker performs essential services for the business, the employer is more likely to have control over their work, indicating an employee relationship. This approach aligns with how the IRS evaluates worker classification.
Common Questions About W-2 and 1099 Forms
Can you receive both a W-2 and a 1099 in the same year?
Yes, it is possible to obtain both forms if you have been employed as a regular employee and also performed work as an independent contractor.
What happens if I don't receive my W-2 or 1099?
Contact your employer if you are still waiting to receive your W-2 by mid-February. For a missing 1099, contact the payer. If you still do not receive your W-2, you can file Form 4852 as a substitute. Form 4852 does not replace a missing 1099-NEC or 1099-MISC, so report that income on your return anyway, using your own records.
How do I report income from a 1099 on my tax return?
Income from a 1099-NEC is reported on Schedule C (Profit or Loss from Business) and may require filing Schedule SE (Self-Employment Tax).
What is the 1099 reporting threshold for 2026?
For payments made in 2026 and later, you generally need to issue a 1099-NEC or 1099-MISC once you pay a worker or vendor $2,000 or more in a calendar year. The old threshold was $600. The $2,000 amount can be adjusted for inflation starting in 2027, and some payments, such as royalties of $10 or more, have their own lower thresholds. See the IRS instructions for Forms 1099-MISC and 1099-NEC for the full list.
When are W-2 and 1099 forms due in 2027?
For the 2026 tax year, the W-2 and 1099-NEC deadline is Monday, February 1, 2027, because January 31 falls on a Sunday. That date applies to sending copies to employees and contractors and to filing W-2s with the Social Security Administration. Form 1099-MISC copies to recipients are also due February 1. Filing 1099-MISC with the IRS is due March 1, 2027 on paper (February 28 is a Sunday) or March 31, 2027 electronically.
Do I have to e-file 1099s?
Yes, if you file 10 or more information returns of all types combined in a year. That count includes W-2s, 1099s and other forms together, so many employers with even a small team have to e-file. Smaller filers can still file on paper with Form 1096. The IRS explains the requirement on its e-file information returns page.
What happens if I classify an employee as a 1099 contractor by mistake?
Misclassifying an employee as an independent contractor can lead to back payroll taxes, penalties and interest, and you may owe the employee’s unpaid benefits and protections. The IRS looks at behavioral control, financial control and the type of relationship to decide a worker’s status, not just the form you issued. Review the IRS guidance on independent contractors vs. employees before you issue the form.
How APS Simplifies Tax Form Management
Managing and distributing tax forms can be complex and time-consuming, but APS is here to help. Our unified payroll and HR solution streamlines the process, ensuring accuracy and compliance. Here’s how APS can assist:
- Automated Tax Form Generation: Easily generate and distribute W-2 and 1099 documents to your workers and independent contractors.
- Compliance and Accuracy: Ensure all tax forms are accurate and compliant with federal and state regulations.
- Employee Self-Service: Allow employees and contractors to access their tax forms online anytime.
Practical Scenarios and Examples
Full-Time Employee with a Side Gig
Jane works full-time at a marketing agency and receives a W-2 form at the end of the year. She does freelance graphic design work on weekends, for which she receives a 1099-NEC. Jane must report both forms on her tax return, detailing her wages and non-employee compensation.
Freelancer with Multiple Clients
John is a freelance writer who works for several clients yearly. Each client provides him with a 1099-NEC form reporting the income paid to him. John must keep track of his income and expenses, filing a Schedule C to report his business earnings and a Schedule SE to pay self-employment taxes.
Employer with Mixed Workforce
XYZ Corp employs a mix of full-time employees and independent contractors. The company issues W-2 forms to its employees and 1099-NEC forms to its contractors. To streamline this process, XYZ Corp uses APS to automate the generation and distribution of these tax forms, ensuring timely and accurate filing.
Demystifying Tax Forms: W-2s and 1099s
Knowing the difference between W-2 and 1099 forms is key to accurate tax reporting and compliance. Understanding which form to use helps ensure proper classification and fewer year-end headaches.
Sources
- About Form W-2, Wage and Tax Statement
- About Form 1096, Annual Summary and Transmittal of U.S. Information Returns
- About Form 1099-NEC, Nonemployee Compensation
- About Form 1099-MISC, Miscellaneous Information
- Instructions for Forms 1099-MISC and 1099-NEC (12/2026)
- E-file Information Returns
- Topic No. 307, Backup Withholding
- Independent Contractor (Self-Employed) or Employee?
- Employee (Common-Law Employee)
- Behavioral Control
- Financial Control
- Type of Relationship
- Publication 15-A (2026), Employer’s Supplemental Tax Guide
- How to Fill W-2 Form (PDF Expert)