A fringe benefit is any form of compensation an employer provides to an employee beyond regular wages — health insurance, retirement contributions, tuition assistance, or a company car are common examples. The IRS defines fringe benefits as “a form of pay for services,” and treats them as taxable income unless the law specifically excludes them.
This guide covers what counts as a fringe benefit, which benefits are taxable versus nontaxable, how to value them for payroll, and how to report them correctly, based on the IRS’s official Employer’s Tax Guide to Fringe Benefits (Publication 15-B).
Disclaimer: This overview is for general education only. Always confirm details with your CPA or tax advisor.
What Counts as a Fringe Benefit?
Fringe benefits span a wide range beyond the basics above — commuter subsidies, dependent care assistance, tuition assistance, cell phones, company cars, and more. Some of these are required by law, while others are entirely optional, offered at the employer’s discretion to support recruiting and retention.
Legally Required Benefits & Employer Payroll Obligations.
-
Social Security and Medicare (FICA):
Employers and employees contribute to covered wages, and taxable fringe benefits are generally subject to FICA.
-
Unemployment insurance (FUTA/SUTA):
Employer-paid employment taxes that fund benefits for qualified unemployed workers.
-
Health benefits / medical leave under federal law:
Large Applicable Employers must offer health insurance that meets ACA requirements. FMLA provides job-protected leave and continuation of group health benefits.
-
Workers’ compensation:
State programs covering work-related injuries and illnesses.
Common Optional Benefits (high-impact)
-
Group-term life insurance
-
Retirement plan matches
-
Transportation/parking subsidies
-
Tuition assistance and professional development
-
Gym memberships and wellness stipends
-
Equity/Employee Stock Options
-
Childcare/Dependent care assistance
-
Cell phones, internet stipends, equipment
Are Fringe Benefits Taxable?
General rule: A fringe benefit is taxable and must be included in wages unless the law specifically excludes it. When taxable, it’s usually subject to income tax withholding, Social Security, and Medicare, and reported on Form W-2 (often Box 14 for description).
Standard nontaxable exclusions (when IRS conditions are met):
-
Employer-paid health insurance premiums and many medical reimbursements
-
De minimis benefits (low-value, infrequent)
-
Qualified transportation fringes (subject to monthly limits)
-
Group-term life insurance up to $50,000
-
Qualified moving expense reimbursements (limited cases)
-
Working condition fringes (e.g., business use of a phone or tools)
-
Qualified dependent care assistance (e.g., a Dependent Care FSA within annual limits)
Common taxable examples:
-
Cash bonuses and gift cards
-
Personal use of a company car (outside business use rules)
-
Group-term life insurance over $50,000
-
Some club dues, prizes, and awards that don’t meet IRS requirements
Publication 15-B gives the precise criteria for each exclusion and whether employment taxes and income tax withholding apply.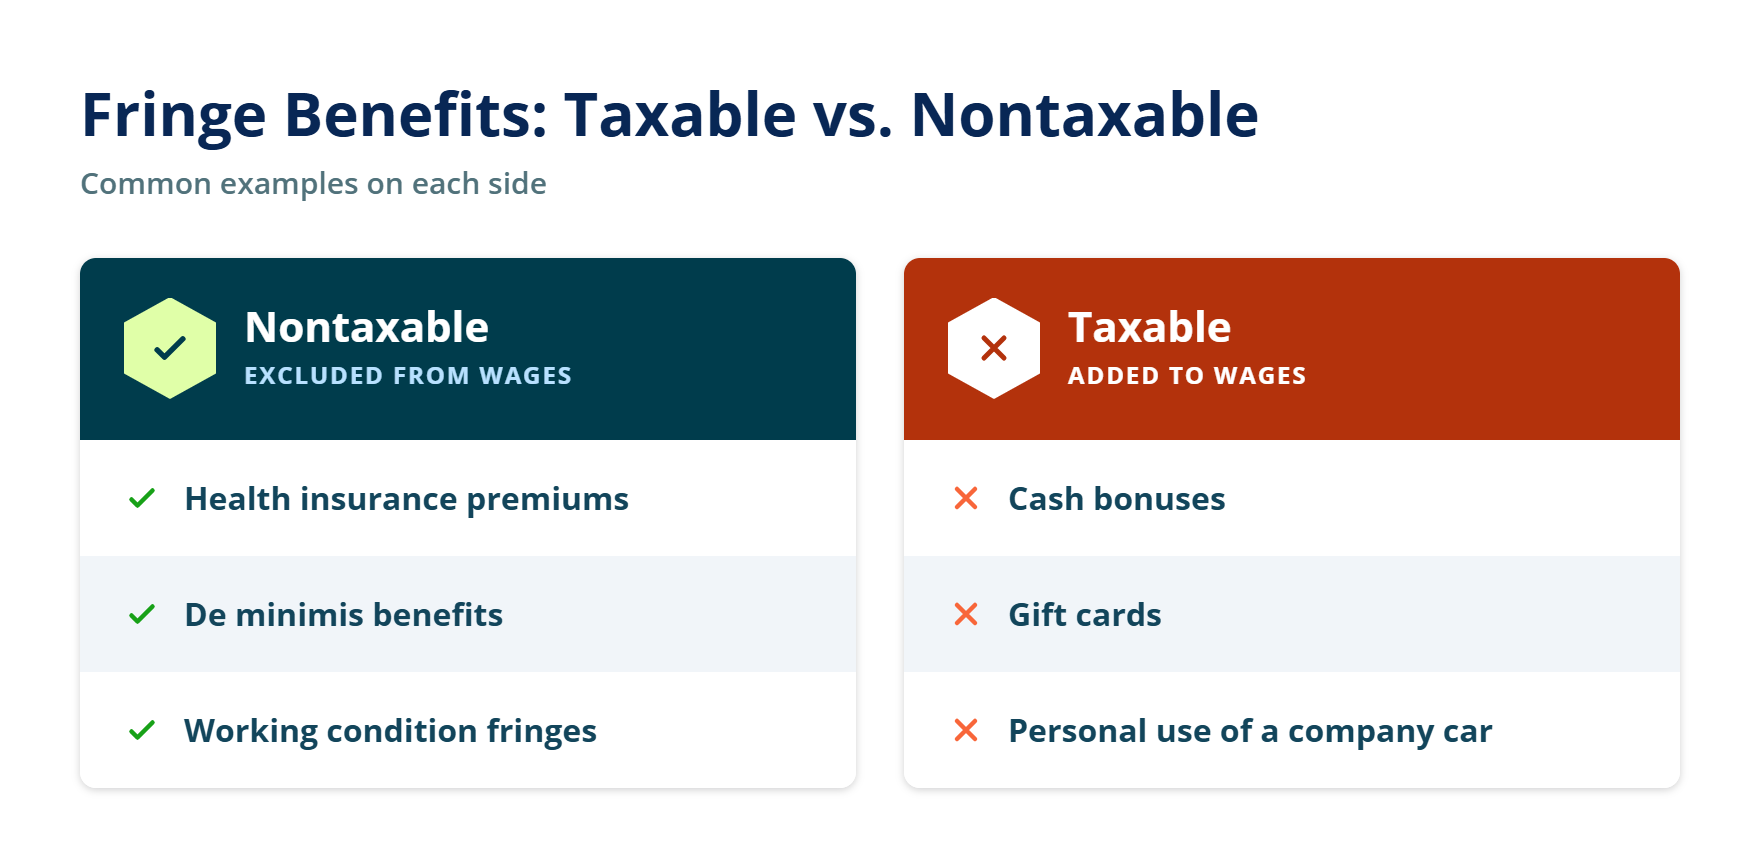
Valuing Fringe Benefits (Fair Market Value)
To calculate taxability, determine the fair market value (FMV): what a willing buyer would pay for the benefit. Examples:
-
Gym access
Use the local annual membership price (less any employee after-tax share)
-
Company car personal miles
Use IRS special valuation methods
-
Cell phones are often used for substantial business reasons
Often a working condition fringe (nontaxable) if used primarily for business
Taxable amount = FMV − any amount the employee paid with after-tax dollars − any legally excludable portion.
Accountable Plans: Reimbursements Done Right
Use an accountable plan to reimburse business expenses (travel, mileage, tools, home-office items for eligible roles) without creating taxable income. To qualify:
-
Expenses have a business connection.
-
Employees substantiate amounts, time, place, and purpose in a reasonable period.
-
Employees return excess advances.
If these conditions aren’t met, reimbursements become taxable wages subject to income tax withholding and employment taxes.
Tax-Advantaged Benefits to Consider
These programs can lower taxable pay for employees and reduce payroll tax exposure for employers:
-
Health benefits through Section 125 cafeteria plans (pre-tax premiums, HSAs/HRA/FSAs where eligible)
-
Dependent care assistance (e.g., a DCAP/FSA) up to annual IRS limits
-
Commuter benefits (transit/parking) within monthly caps
Follow the plan document and nondiscrimination rules to keep these benefits pre-tax.
How to Handle Fringe Benefits in Payroll
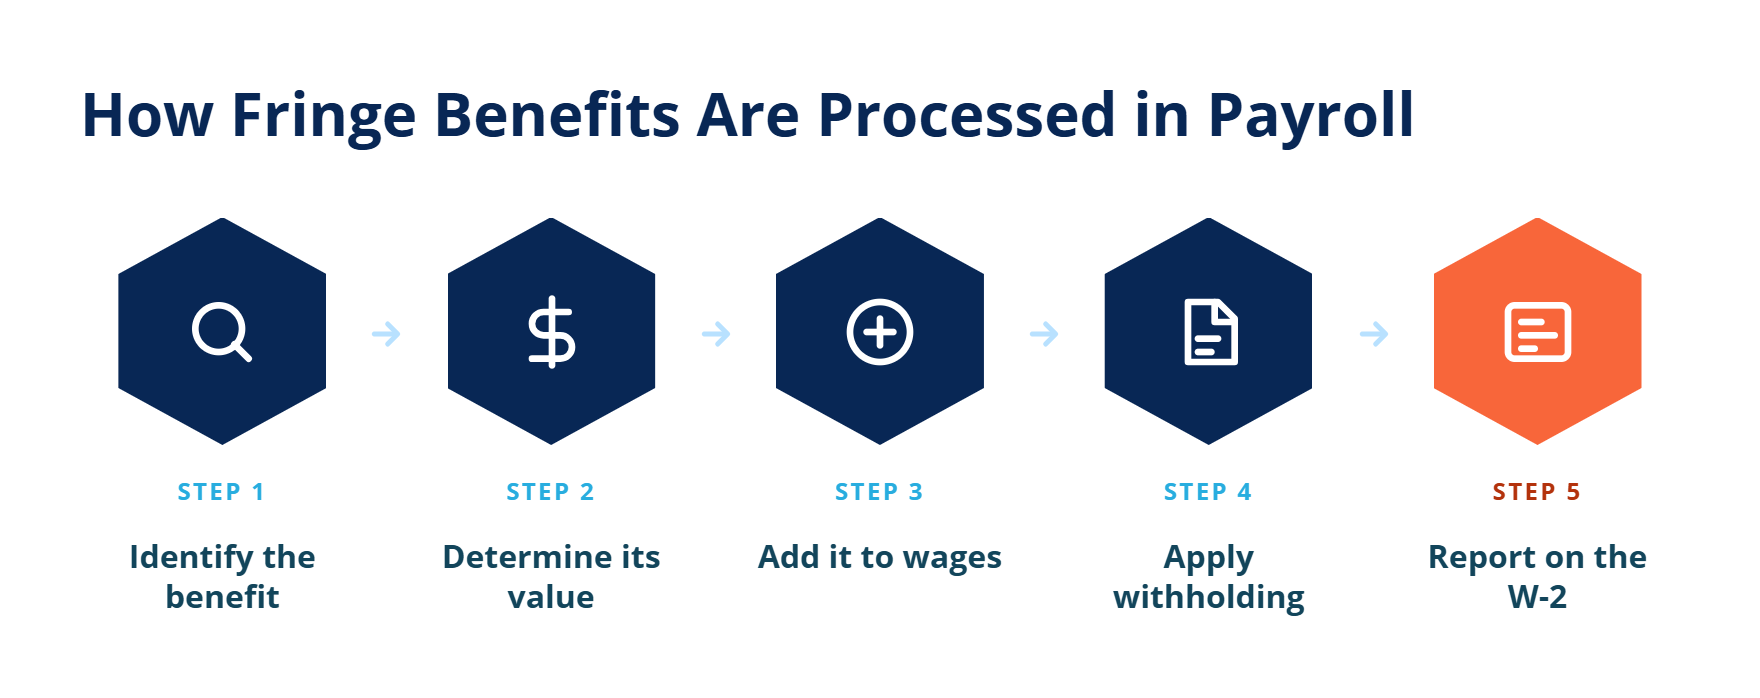
Taxable fringe benefits are processed as imputed income:
-
Identify the benefit and determine if it’s taxable under Publication 15-B
-
Value the benefit (FMV minus employee after-tax payments and excludable amounts)
-
Add the taxable value to wages for the period (monthly/quarterly/annually)
-
Apply income tax withholding (or consider the “no-withholding” option for certain benefits, then withhold later in the year), plus Social Security and Medicare if applicable
-
Report on Form W-2 (often in Box 1, 3, and 5 as required; description can go in Box 14)
Timing tip: Publication 15-B allows you to add taxable fringe values to payroll periodically or as a year-end lump sum, as long as withholdings and deposits are handled correctly.
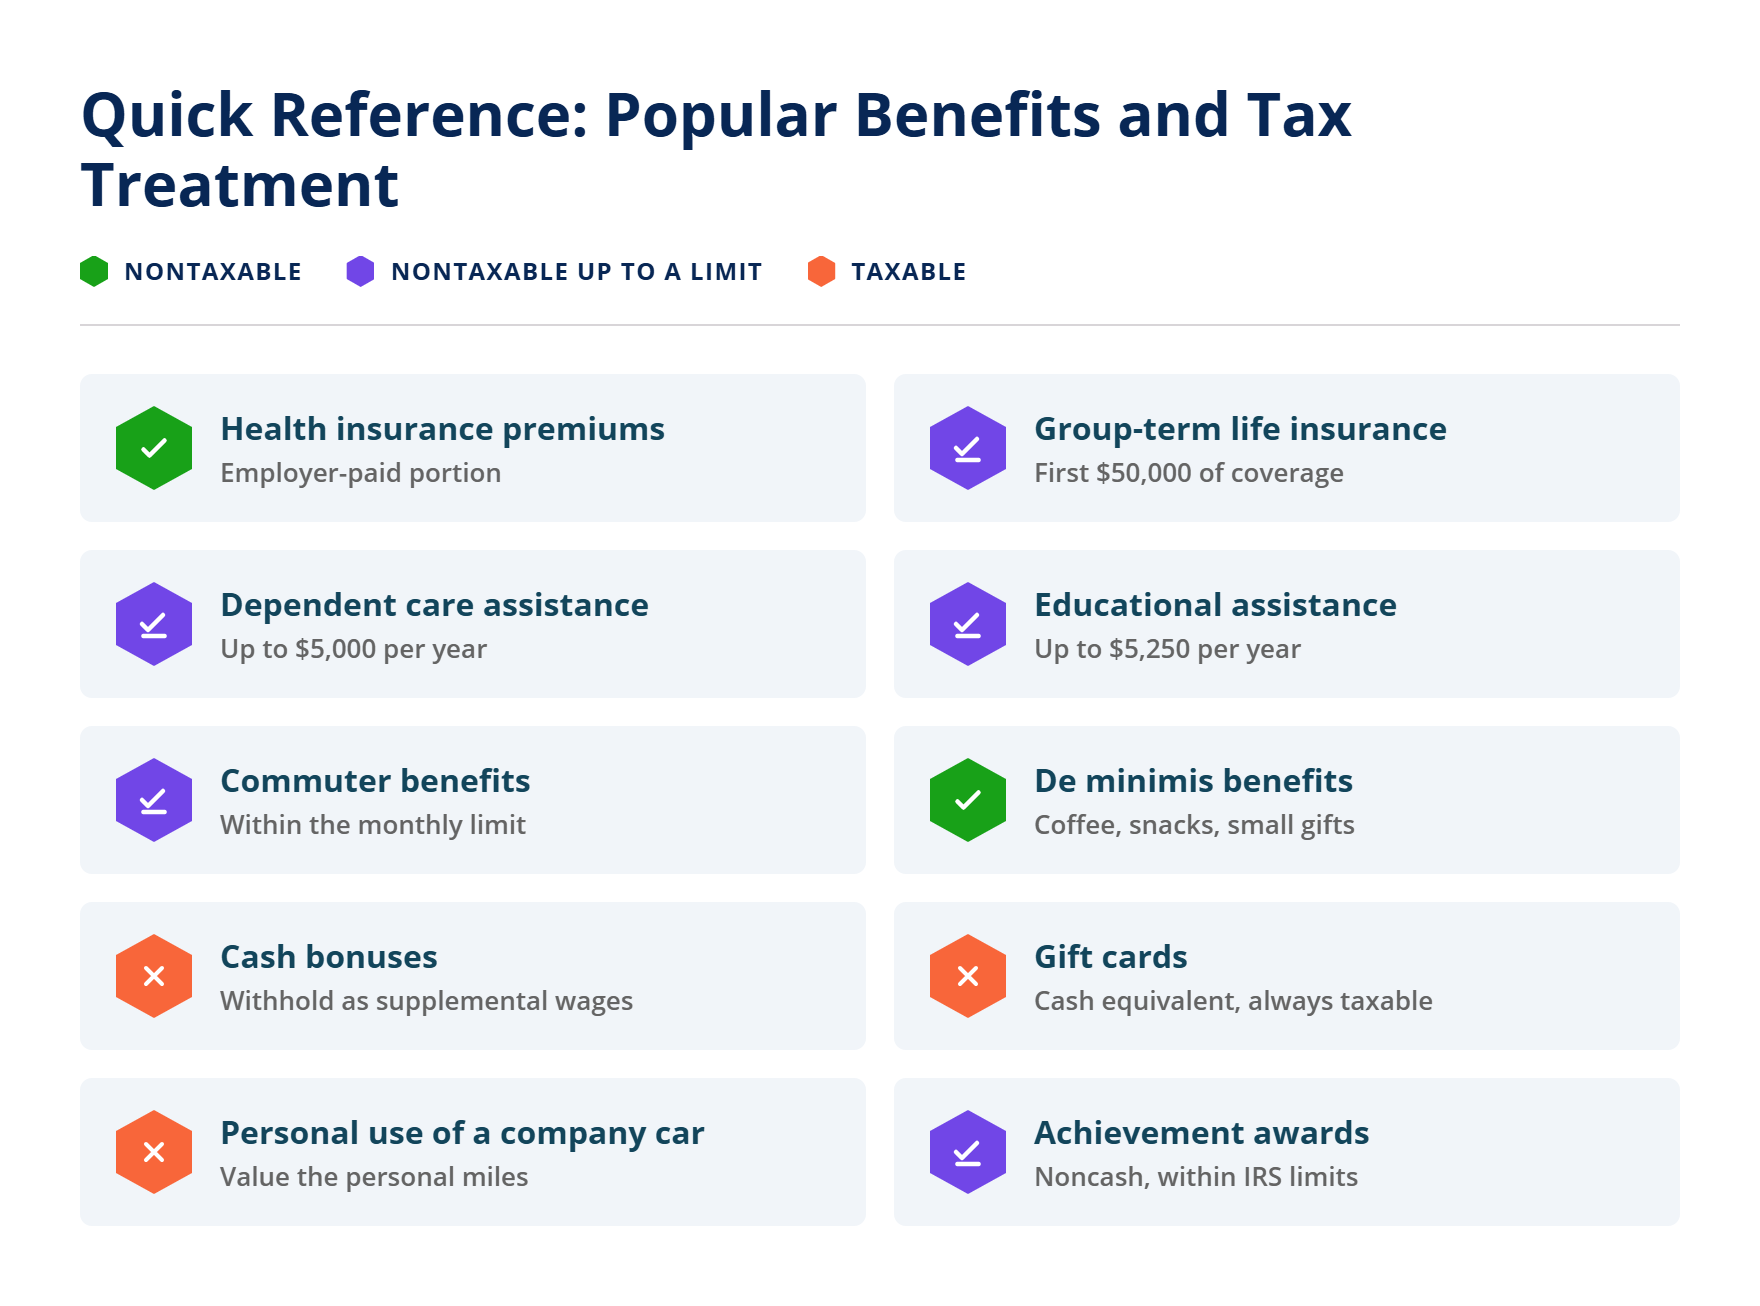
Quick Reference: Popular Benefits and Typical Tax Treatment
-
Employer health insurance premiums:
Generally nontaxable to the employee; subject to ACA rules
-
HSA contributions:
Employer HSA contributions: Generally excluded from wages for eligible employees up to IRS contribution limits; report employer contributions on Form W-2, Box 12 using Code W
-
Dependent care benefits:
Nontaxable up to the annual limit if provided under a qualified plan; excess is taxable.
-
Group-term life insurance:
Nontaxable up to $50,000; above that, imputed income using IRS tables.
-
Commuter/parking benefits:
Amounts above the applicable monthly exclusion limit are taxable.
-
Bonuses/gift cards:
Taxable wages, always.
-
Personal use of company car:
Taxable unless excluded; use IRS valuation methods.
-
Achievement awards:
Potentially nontaxable if tangible property and within dollar limits for qualified plans.
Always confirm specifics in Publication 15-B—it’s the definitive tax guide to fringe benefits.
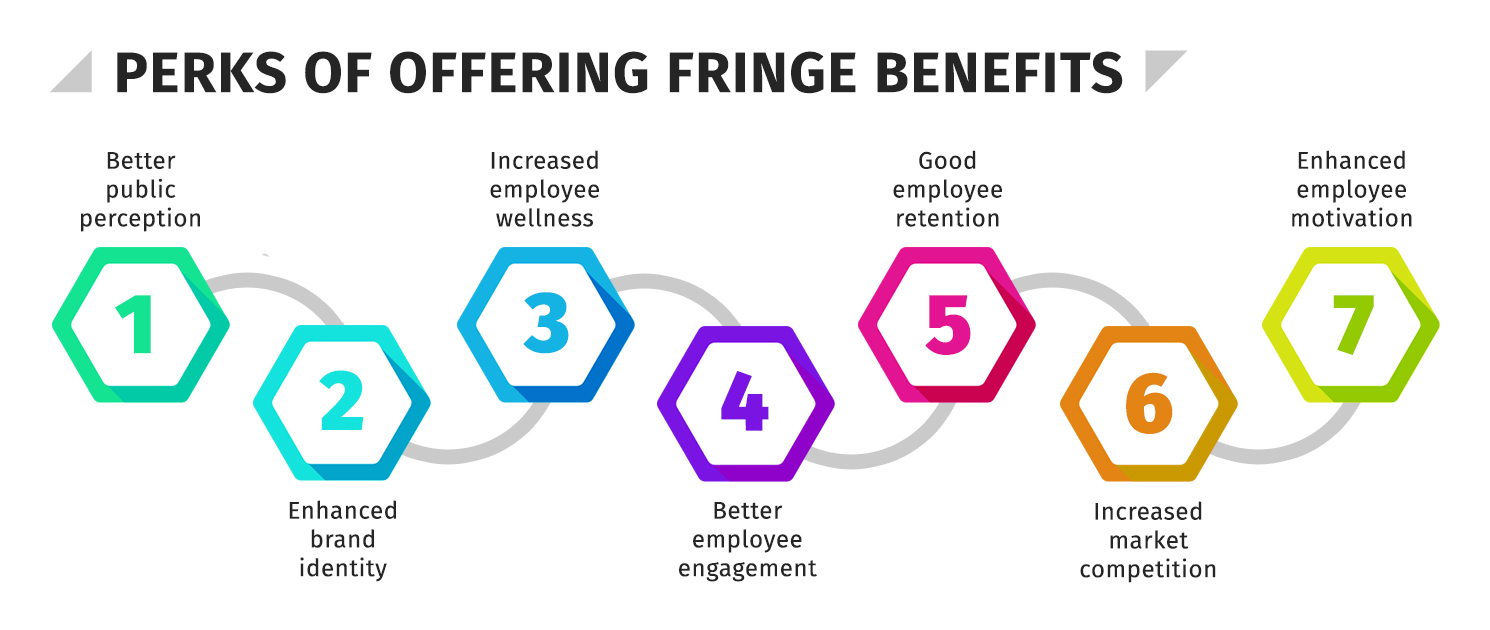
Why Offer Fringe Benefits?
Done right, benefits:
-
Strengthen recruiting and retention
-
Boost morale and wellness
-
Support productivity with the right health benefits and flexibility
-
Provide tax efficiency through pre-tax programs and thoughtful plan design
Frequently Asked Questions
Are fringe benefits taxable?
Fringe benefits are taxable by default unless the IRS specifically excludes them. Common nontaxable exceptions include employer-paid health insurance premiums, de minimis benefits, and working condition fringes. When a benefit is taxable, it’s subject to income tax withholding, Social Security, and Medicare, and it must be reported on the employee’s Form W-2.
Is a company car considered a fringe benefit?
Yes. The business-use portion of a company car is generally a nontaxable working condition fringe, while any personal use of the vehicle is taxable and must be valued using IRS special valuation methods.
What is the tax-free limit for group-term life insurance?
Employers can provide up to $50,000 in group-term life insurance coverage tax-free. Coverage above that amount is taxable to the employee, with the taxable value calculated using IRS Table I rates.
What is a de minimis fringe benefit?
A de minimis fringe benefit is a low-value, infrequent perk that’s impractical to account for, such as occasional snacks, small holiday gifts, or occasional personal use of a copy machine. Because of their minimal value, these benefits are excluded from an employee’s taxable income.
How are fringe benefits reported on a W-2?
Taxable fringe benefits are generally included in Box 1 of Form W-2 and in Boxes 3 and 5 when applicable. Some benefits have additional reporting requirements, while employers may use Box 14 to provide supplementary fringe-benefit information.
Do employers have to offer fringe benefits?
Some benefits are legally required, including Social Security and Medicare (FICA), unemployment insurance, workers’ compensation, and, for applicable large employers, health coverage under the ACA. Most other fringe benefits, like retirement matches, tuition assistance, or wellness stipends, are optional and offered at the employer’s discretion to support recruiting and retention.
Where APS Fits In
Tracking who gets which benefit—and when it becomes taxable—can get messy. APS helps you simplify:
-
Store benefit settings and apply them during payroll runs
-
Add imputed income items (monthly, quarterly, or year-end)
-
Automate recurring items and reduce manual keying errors
-
Keep reporting aligned with employment taxes and W-2 requirements
Your CPA can calculate benefit values; APS makes applying income tax withholding, Social Security, and Medicare straightforward inside payroll.
Sources
- Publication 15-B (2026), Employer’s Tax Guide to Fringe Benefits | IRS
- Employer Costs for Employee Compensation | U.S. Bureau of Labor Statistics
- What Is Taxable and Non-Taxable Income? | IRS
- Group-Term Life Insurance | IRS
- Fringe Benefit Guide | IRS
- Publication 463, Travel, Gift, and Car Expenses | IRS
- FAQs for Government Entities Regarding Cafeteria Plans | IRS
- Publication 969, Health Savings Accounts and Other Tax-Favored Health Plans | IRS
- Form W-2 Reporting of Employer-Sponsored Health Coverage | IRS
- Employee Fringe Benefits Increase Job Satisfaction | Wolters Kluwer